
Deregulated Energy States in 2026: Where Business Energy Buying Strategies Still Pay Off
As the fourth quarter of 2026 approaches, commercial energy buyers are entering a critical winter procurement window. The timing is significant for businesses operating in PJM, where the 2026/27 capacity auction cleared at $329.17 per megawatt-day and the 2027/28 auction cleared at $333.44 per megawatt-day.
New Jersey businesses have also reported 17% to 20% increases in supply costs during 2026. Those increases are market context, not the complete story. The more important issue is that energy costs now depend on location, wholesale market design, capacity exposure, transmission constraints, and contract structure.
The right deregulated energy states energy buying strategies therefore differ by state and market. A fixed-price approach that works for a Pennsylvania warehouse may be unsuitable for a Texas data center or a New York hotel portfolio.
1. Choice Versus Monopoly: What Deregulation Actually Means
In a traditional regulated utility market, one utility generally provides both:
Electricity supply
Delivery through poles, wires, and meters
Default service under rates approved by state regulators
In a deregulated or restructured market, those functions are separated:
The local utility continues to deliver electricity and maintain infrastructure.
Competitive suppliers offer the electricity supply component.
The business can compare suppliers, contract terms, and purchasing structures.
Utility delivery charges remain regulated and continue through the local distribution company.
The term deregulated is used broadly. Some states offer retail choice to nearly all customer classes, while others limit participation to larger commercial and industrial accounts or specific utility territories.
According to the U.S. Energy Information Administration, approximately 19 states plus Washington, D.C. allow at least some commercial or industrial customers to select competitive electricity suppliers. The exact count varies depending on whether a source includes limited, capped, or territory-specific programs.
The practical distinction is simple: choice creates procurement options, but it does not eliminate wholesale market risk.
2. The Major 2026 Markets and What Each Requires
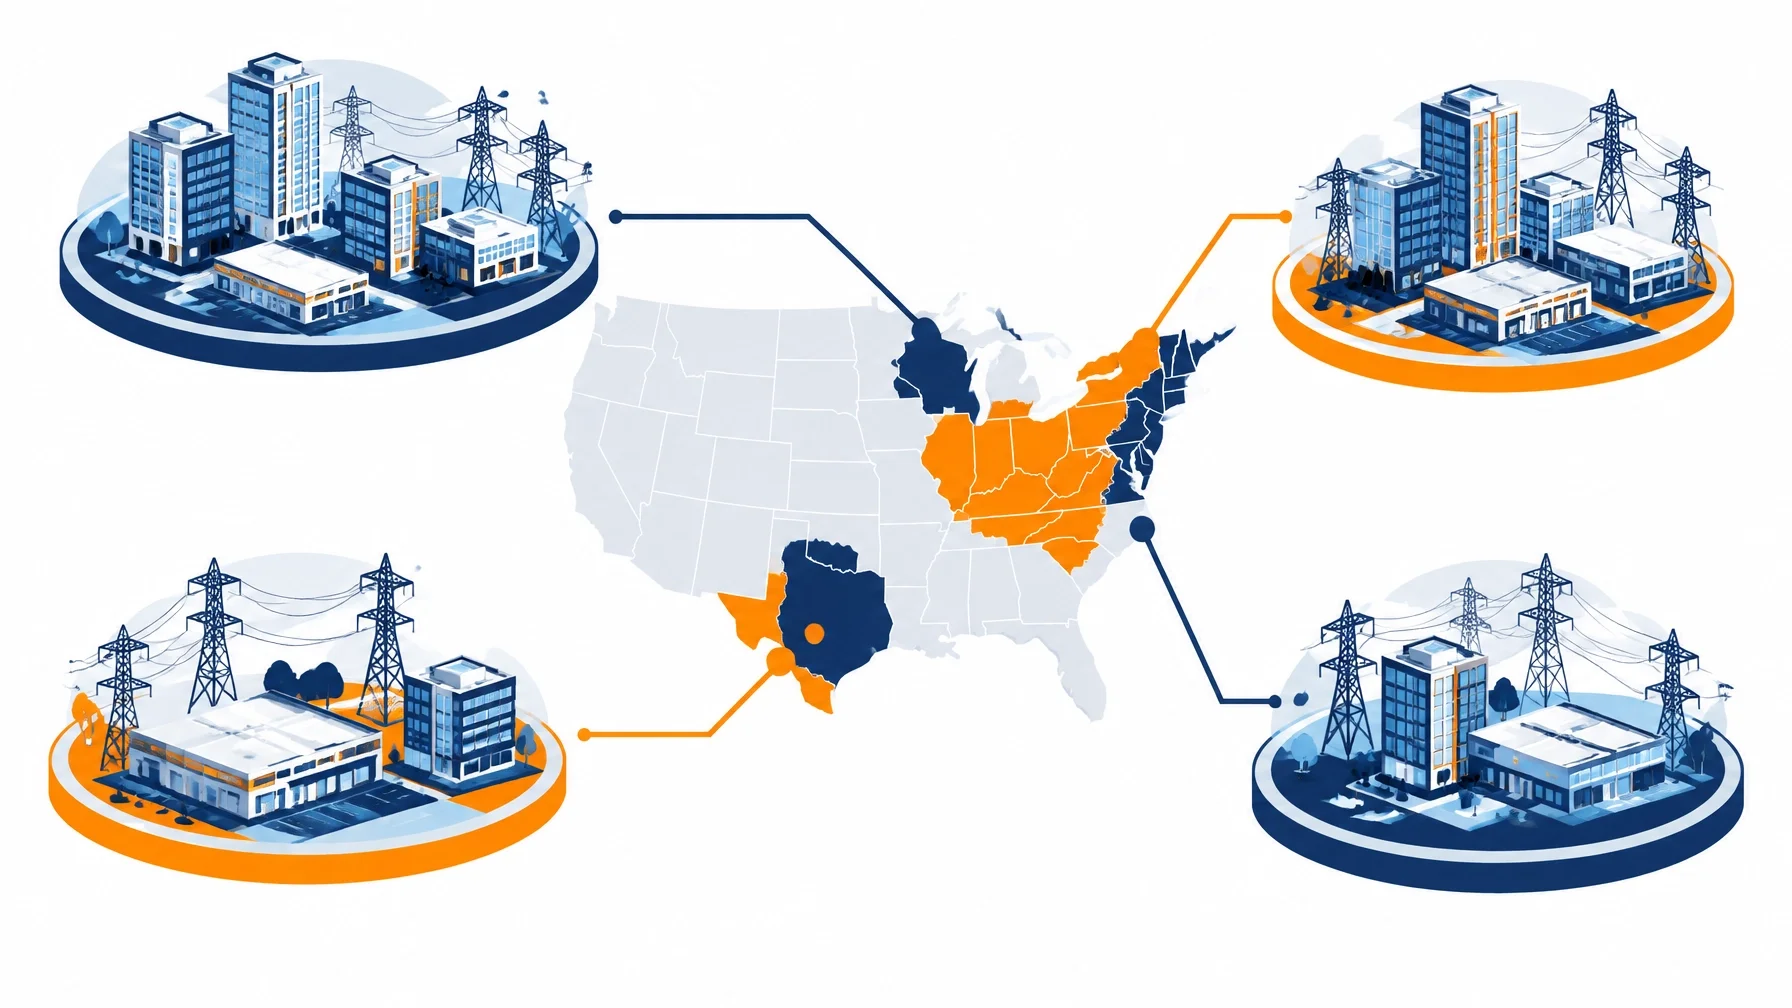
PJM: DE, IL, MD, NJ, OH, PA, and Washington, D.C.
PJM is the most important market for many businesses in the Mid-Atlantic and parts of the Midwest. Its broad commercial-choice states include:
Delaware
Illinois, primarily within applicable competitive utility territories
Maryland
New Jersey
Ohio
Pennsylvania
Washington, D.C.
PJM also covers portions of states such as Virginia and Michigan, but commercial choice in those states is more limited.
The defining 2026 issue is capacity. PJM’s 2026/27 auction cleared at $329.17/MW-day, compared with $269.92/MW-day for 2025/26 and $28.92/MW-day for 2024/25. The 2026/27 delivery year runs from June 2026 through May 2027, which includes winter 2026.
For a PJM buyer, procurement requires analysis of:
Peak Load Contribution and capacity obligation
Supplier treatment of capacity costs
Zonal congestion exposure
Facility demand patterns
Winter operating requirements
Contract timing before delivery-year costs increase
State-specific view:
New Jersey: Active supplier competition, but elevated PJM capacity costs make timing and capacity treatment central to the buying decision.
Pennsylvania: One of the deepest commercial supplier markets; buyers can compare fixed, indexed, and blended structures across multiple utility territories.
Ohio: Strong commercial supplier participation and aggregation activity; businesses should compare offers using consistent usage and demand assumptions.
Maryland: Competitive choice exists across major utility territories, with PJM capacity and transmission costs affecting final pricing.
Illinois: Market exposure varies because the state spans multiple utility and wholesale market territories. The delivery territory must be identified before comparing rates.
Delaware: Smaller market depth than Pennsylvania or New Jersey, but PJM exposure remains the primary procurement consideration.
Washington, D.C.: A compact PJM market where portfolio aggregation and contract administration can be more important than supplier volume alone.
ERCOT: Competitive Texas Territories
Texas is one of the most competitive commercial electricity markets in the United States, but retail choice is not universal. Customers served by municipal utilities and electric cooperatives, including major systems such as Austin Energy and CPS Energy, generally do not participate in the same competitive retail structure.
ERCOT operates without a centralized capacity market. Instead, the market relies heavily on energy pricing and scarcity signals. That creates a different risk profile:
No standard centralized capacity charge
Greater exposure to wholesale energy volatility
Significant importance of weather and system conditions
Higher consequences for poorly structured indexed exposure
Strong value from load flexibility, storage, and on-site generation
Texas buyers often prioritize fixed pricing, block purchases, risk caps, or hybrid structures that reduce exposure during extreme summer and winter events.
ISO-NE: CT, ME, MA, NH, and RI
The ISO-New England region includes six states, but Vermont is generally treated as regulated for retail electricity purposes. Commercial choice is most relevant in:
Connecticut
Maine
Massachusetts
New Hampshire
Rhode Island
ISO-NE operates a Forward Capacity Market. Capacity costs are generally lower than the current PJM level, but winter reliability and fuel availability remain significant considerations.
Businesses in ISO-NE should evaluate:
Winter-peaking usage
Capacity and transmission components
Utility territory
Natural gas and generation constraints
Contract flexibility for seasonal operations
Massachusetts and Connecticut typically provide deeper supplier competition than Maine or Rhode Island. However, a smaller market does not necessarily mean a less competitive quote. Load size, credit profile, and usage consistency also affect supplier participation.
NYISO: New York State
New York provides commercial electricity choice through energy service companies, but the market is highly location-sensitive.
The primary distinction is between:
Upstate zones with greater generation availability
Downstate zones, including New York City and Long Island, where transmission constraints and local reliability requirements can increase costs
NYISO uses an Installed Capacity market with seasonal capability periods, monthly auctions, and spot mechanisms. A business electricity rate that appears competitive in an upstate zone may not translate to a downstate facility.
New York buyers should evaluate:
Zone J and Zone K exposure for downstate properties
Seasonal load patterns
Capacity obligations
Congestion risk
Portfolio differences between urban and upstate facilities
3. Other States With Limited or Specialized Commercial Choice
Not every state with competitive energy programs functions like New Jersey, Texas, or Pennsylvania.
Businesses should separately review eligibility in:
Virginia: Larger commercial and industrial customers may qualify under specific demand thresholds.
Michigan: Choice is capped, and participation is concentrated among commercial and industrial customers.
California: Direct Access is limited and subject to program rules and utility territory.
Oregon, Georgia, and Nevada: Certain commercial programs exist, but availability varies by customer class, utility, and location.
The state name alone is not enough to determine eligibility. The analysis must identify the utility, service territory, meter type, annual usage, peak demand, and applicable state rules.
4. How to Build a State-by-State Buying Strategy
A multi-state business should not use one national strategy for every location. Each facility should be assigned a market profile based on its wholesale region and operating characteristics.
Fixed procurement
A fixed structure can support predictable budgeting for:
Hotels with stable occupancy patterns
Office and retail portfolios
Manufacturing sites with consistent production schedules
Businesses with strict operating budgets
The analysis should confirm which cost components are included, how capacity is calculated, and whether the quoted rate applies to every meter.
Block and index
Block-and-index procurement combines:
Fixed-price blocks for predictable baseline usage
Market-indexed pricing for variable consumption
This structure can work for manufacturers, data centers, and multi-site portfolios with measurable base load and uncertain expansion. It requires accurate hourly or interval usage data.
Laddering
Laddering divides future purchases across multiple dates rather than making one decision at a single market price. A business may secure portions of expected usage over several months or delivery years.
Laddering can reduce timing risk, particularly in PJM and ISO-NE, where capacity and forward energy costs may remain elevated. It also supports multi-year budgeting without requiring the business to forecast one perfect purchase date.
Hybrid procurement
A hybrid strategy combines fixed and indexed components based on facility risk:
Fixed pricing for essential base load
Indexed exposure for flexible operations
Separate treatment for expansion load
Different terms for different states or market zones
For example, a data center may require greater price certainty for its contracted base load, while a manufacturing facility may retain market exposure for production that can be shifted or curtailed.
The correct structure depends on cash flow, credit requirements, operating flexibility, expansion plans, and tolerance for price volatility.
5. Why Data Matters More Than the Advertised Rate
A commercial energy comparison should use at least 12 months of billing data, with 24 months preferred. The file should include:
Monthly and interval kWh usage
Peak kW demand
Capacity obligation or PLC
Current supplier and expiration date
Utility territory
Seasonal load changes
Planned openings, closures, or expansions
Facility operating schedules
This information allows suppliers to price the same load assumptions. It also helps identify whether savings result from a lower commodity rate, a different usage forecast, reduced peak exposure, or a change in billing treatment.
United Energy Consultants’ Energy Tracker Pro-focused utility management approach helps multi-site businesses organize utility information, monitor consumption, and compare actual performance against procurement assumptions.
6. Why an Independent Consultant Matters in a Multi-State Portfolio
Supplier relationships can influence which products and offers a buyer sees. An independent consultant with no supplier affiliations can evaluate competing structures based on the customer’s load profile rather than a supplier’s preferred product.
United Energy Consultants provides:
Competitive commercial energy procurement
Usage-based buying strategies
Supplier negotiations across deregulated states
Contract and cost-component analysis
Portfolio-level utility management
Energy Tracker Pro support
Ongoing account management
The company has more than 20 years of energy-market experience, maintains relationships with more than 80 suppliers, and provides services with zero out-of-pocket costs to clients.
Businesses can also review United Energy Consultants’ commercial electricity rate comparison guide and fall 2026 procurement playbook.
7. The Q4 2026 Procurement Checklist
Before the coldest demand months arrive, a multi-state business should:
Confirm each contract expiration date.
Identify every utility and wholesale market territory.
Gather 12 to 24 months of usage history.
Review capacity obligations and peak demand.
Compare fixed, block-and-index, laddered, and hybrid options.
Model PJM capacity exposure for winter 2026.
Separate base load from expansion or variable load.
Compare supplier proposals using the same usage assumptions.
Review each facility independently before aggregating the portfolio.
Establish a monitoring process after contracts are executed.
PJM’s elevated capacity pricing makes winter procurement especially time-sensitive for businesses in New Jersey, Pennsylvania, Maryland, Delaware, Ohio, Illinois, and Washington, D.C. ERCOT buyers face a different challenge: managing energy price volatility without a centralized capacity market. ISO-NE and NYISO buyers must focus on winter reliability, capacity, and location-specific constraints.
United Energy Consultants offers a free, usage-based analysis for businesses evaluating energy costs across one or multiple states. Visit www.uecnow.com to review current usage, compare procurement options, and build a market-specific strategy before winter demand intensifies.